izharshah.com/tools/50000-after-tax · Tax year 2026/27, verified against GOV.UK 21 October 2026
£50,000 after tax:
your take-home pay
About £39,520 a year, £3,293 a month, in the 2026/27 tax year. Change any figure and the page recalculates.
Your full breakdown
| Period | Gross | Take-home |
|---|
| Tax band | Amount taxed | Rate | Tax |
|---|
Your next £1,000
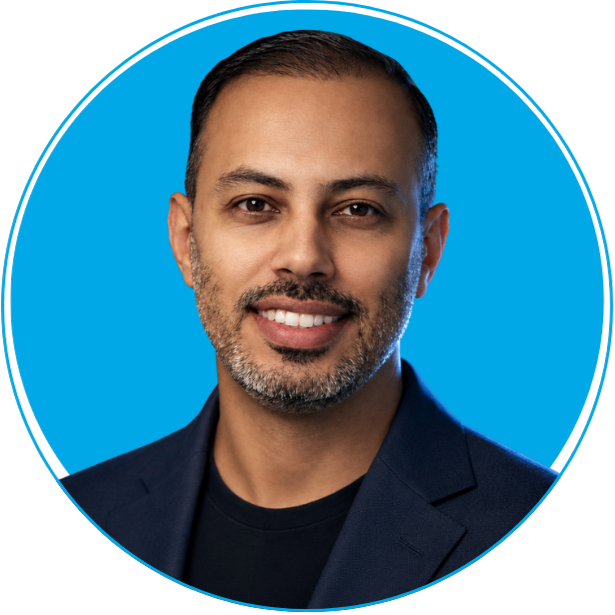
Izhar Shah
PhD in Engineering. Imperial College London, Jaguar Land Rover, and a business built while employed that reached £500,000 in its first 12 months. Get on the list and every new tool, idea and step-by-step guide lands in your inbox on Monday morning.
Thank you, you are on the list.
How this calculator works
The tool applies the 2026/27 rules published by HM Revenue and Customs. The first £12,570 of your salary is the personal allowance and is not taxed. Above that, income tax is charged in bands: 20 per cent basic rate up to £50,270, 40 per cent higher rate up to £125,140, and 45 per cent additional rate beyond it. If you earn more than £100,000 the allowance shrinks by £1 for every £2 of income above that line, which is why the effective rate between £100,000 and £125,140 is 60 per cent.
National Insurance is worked out separately. Employees pay 8 per cent on earnings between £12,570 and £50,270 and 2 per cent above that. Scotland uses its own income tax bands, starting at 19 per cent and rising to 48 per cent, but the same National Insurance rules. Select Scotland above and the page switches bands.
Student loan repayments are 9 per cent of income above your plan threshold (6 per cent above £21,000 for a Postgraduate Loan). Pension contributions here are treated as a net pay arrangement: they reduce the income that is taxed but not the National Insurance you pay. If your employer runs salary sacrifice, your National Insurance would be lower than shown.
Your next £1,000 and the two rates: the donut shows what you would keep from a £1,000 pay rise once tax, National Insurance and any loan repayments are taken. The marginal rate is the share of that £1,000 you lose; the overall rate is tax and National Insurance as a share of your whole salary. Above £50,270 the marginal rate jumps from 28% to 42%, and between £100,000 and £125,140 it reaches 62%.
What it does not cover: tax codes other than the standard 1257L, benefits in kind such as a company car, bonuses paid in a single month, the Welsh rate (currently the same as England), childcare vouchers, or the High Income Child Benefit Charge. It is guidance only and not tax or financial advice. All figures were verified against GOV.UK income tax rates and the employer rates and thresholds on 21 October 2026.
Questions people ask about £50,000 after tax
Is £50,000 a good salary in the UK?
£50,000 is above the UK median full-time salary of about £37,430 (ONS, April 2025). Whether it feels good depends on where you live and what you owe; the take-home of about £39,520 a year is the number to budget from.
How much is £50,000 a month after tax?
About £3,293 a month in England, Wales or Northern Ireland with no pension or student loan, or £3,169 in Scotland.
How much tax do I pay on £50,000?
With a standard tax code you pay about £7,486 income tax and £2,994 National Insurance, a total of £10,480, which is 20.96% of £50,000. Student loans and pension contributions come on top.
What tax band is £50,000 in?
£50,000 sits in the basic rate band. Everything above the £12,570 personal allowance is taxed at 20%, with 8% National Insurance on top. Your next £1,000 straddles the £50,270 higher rate threshold, so you would keep about 62p of it rather than the 72p this band alone would give.
What if I earn a bit more, say £51,000?
On £51,000 you would take home about £40,137 a year.
Nearby salaries and related tools
izharshah.com · Free tools: izharshah.com/tools · Planners and calculators: izharshah.com/store · Contact: izharshah.com/contact